
Content
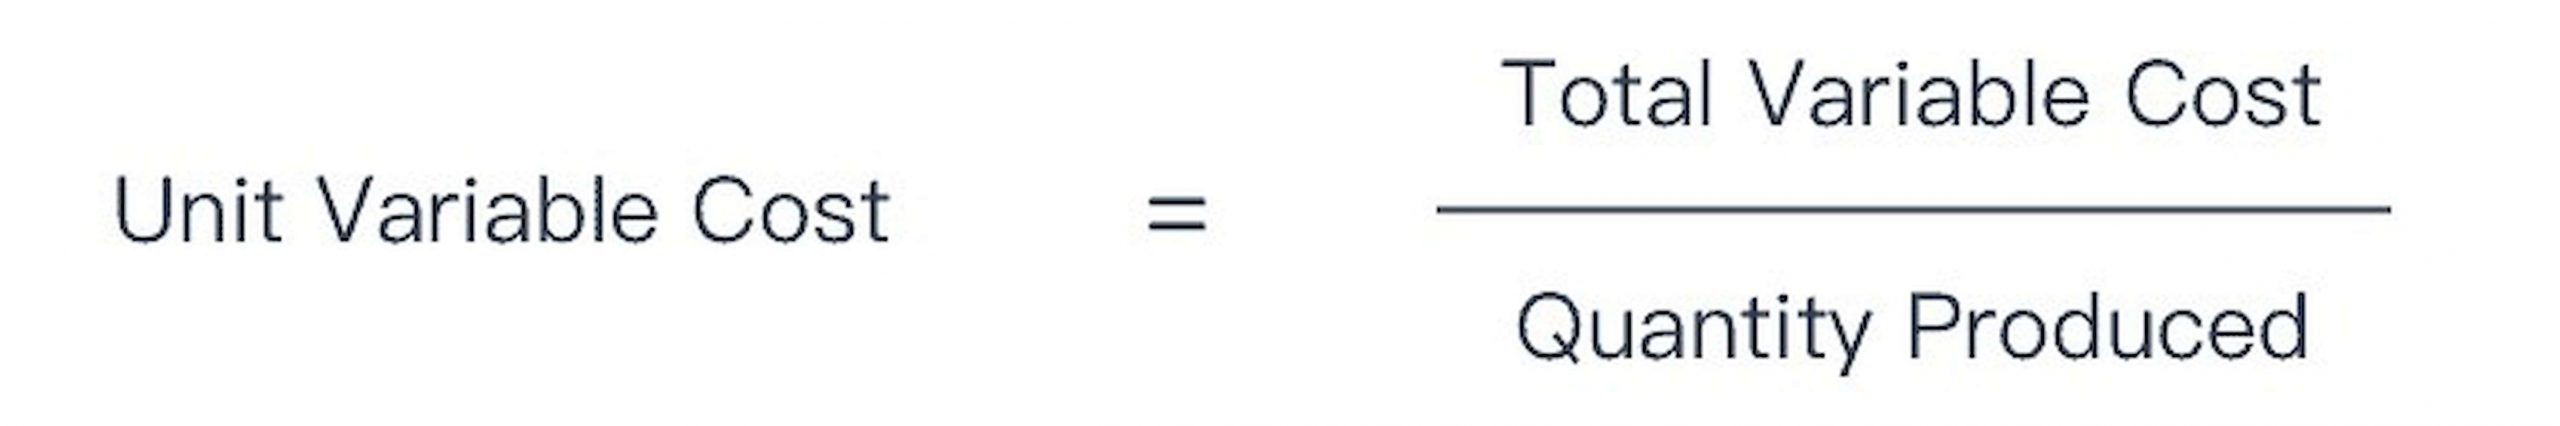
Asset depreciation is an economic phenomenon that results in an impairment of the value of a tangible or intangible asset. Depreciation occurs as the asset’s usefulness diminishes over time, and this decreased value reflects a decrease in the asset’s market value. The primary reasons for depreciation are physical wear and tear, obsolescence, inflation, and changes in market conditions.
- The accumulated depreciation balance increases over time, adding the amount of depreciation expense recorded in the current period.
- Depreciation is an accounting method that spreads out the cost of an asset over its useful life.
- All investments involve risk, including the possible loss of capital.
- Khadija Khartit is a strategy, investment, and funding expert, and an educator of fintech and strategic finance in top universities.
- Accumulated depreciation is shown in the face of the balance sheet or in the notes.
- The journal entries for the accumulated depreciation will help you determine how much of an asset has been written off and its remaining useful life.
Many believe accumulated depreciation goes onto the balance sheet as a negative number, but this is only sometimes accurate. In some cases, accrued depreciation can increase the value of an asset on the balance sheet. Yes, accumulated depreciation goes on the balance sheet as a deduction from the value of an asset. If the item is a service, such as installing a new furnace, the unit is not the physical item but rather the time you spend installing the stove.
Step 1. Balance Sheet Assumptions (Capex, PP&E Useful Life and Salvage Value)
Jim’s Pizza can calculate its total annual depreciation expense by multiplying its yearly depreciation rate by the estimated number of years remaining in the oven’s lifespan. On most balance sheets, accumulated depreciation appears as a credit balance just under fixed assets. In some financial statements, the balance sheet may just show one line for accumulated depreciation on all assets.
Tracking the depreciation expense of an asset is important for reporting purposes because it spreads the cost of the asset over the time it’s in use. The double-declining balance depreciation method is an accelerated method that multiplies an asset’s value by a depreciation rate. The building is expected to be useful for 20 years with a value of $10,000 at the end of the 20th year. The depreciable base for the building is $240,000 ($250,000 – $10,000).
Q1: What is the difference between accumulated depreciation and amortization?
For every asset you have in use, there is an initial cost and value loss over time . For every asset you have in use, there is the “original basis” and then there’s the “accumulated depreciation” . Waggy Tails, a pet grooming company, purchases some equipment with a useful life of 10 years for $110,000. Once the useful life of the equipment is over, Waggy Tails can salvage $10,000. The cost of the PP&E – i.e. the $100 million capital expenditure – is not recognized all at once in the period incurred. Suppose that a company purchased $100 million in PP&E at the end of Year 0, which becomes the beginning balance for Year 1 in our PP&E roll-forward schedule. Accumulated depreciation can shield a portion of a business’s income from taxes.
This information is not a recommendation to buy, hold, or sell an investment or financial product, or take any action. This information is neither individualized accumulated depreciation nor a research report, and must not serve as the basis for any investment decision. All investments involve risk, including the possible loss of capital.
Debit or Credit?
The straight-line method is the simplest method for calculating accumulated depreciation. In this method, you depreciate an asset at an equal amount over each year across its useful life. Now, as Waggy Tails will use the equipment for the next ten years, it will expense the cost of the equipment for the entire period. Using the straight-line depreciation method, Waggy Tails finds that the asset will depreciate by $10,000 a year for the next ten years until its book value is $10,000. Typically, there’s an original basis for every asset you have in use, equal to the original purchase price. Then, there’s accumulated depreciation or the value lost in the asset, which is considered an expense on your books.
- Company A estimates that the vehicle’s useful life is 10 years with no residual value.
- Capital Asset accounts hold the original acquisition cost of long-term fixed assets like buildings, equipment and vehicles.
- Depreciation is often shown on a company’s cash flow statement to provide insight into how much money it spends on its assets each year.
- When you first purchased the desk, you created the following depreciation schedule, storing everything you need to know about the purchase.
- In other words, the accumulated account equals the fixed asset account.
After three years, the company records an asset impairment charge of $200,000 against the asset. At that point, the accumulated depreciation for the asset is $300,000.
Journal Entry
It’s essential to ensure that your repairs and renewals save you money in the long run rather than just providing a visual appearance of being updated or improved. When a company buys an asset, it pays for it in cash and records the purchase price as an asset on its books. Over time, the value of this asset will depreciate, meaning that each year the asset’s weight is reduced by a percentage. The time a purchase has been in operation and the date of acquisition affect how much depreciation is. The Sum of the Years’ Digits depreciation is a method used to calculate the depreciation that should apply to an asset over a given period.
Sunrise New Energy : UNAUDITED CONDENSED CONSOLIDATED BALANCE SHEETS – Form 6-K – Marketscreener.com
Sunrise New Energy : UNAUDITED CONDENSED CONSOLIDATED BALANCE SHEETS – Form 6-K.
Posted: Mon, 12 Dec 2022 22:24:08 GMT [source]